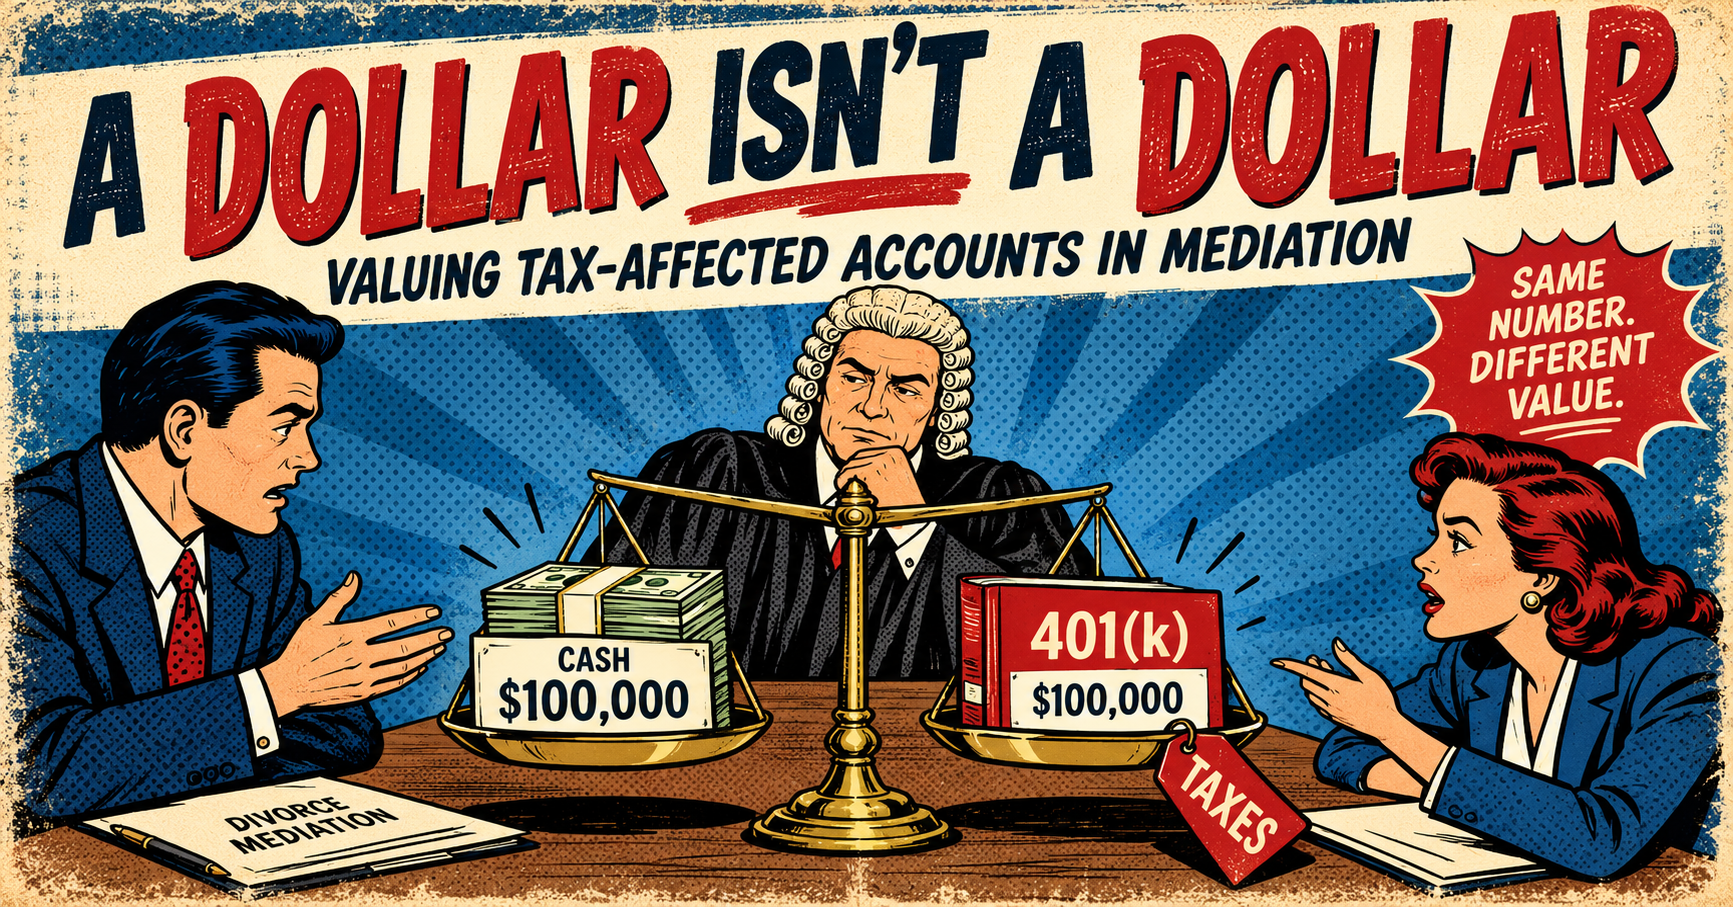
Every mediator has watched it happen. The spreadsheet balances, the parties start packing up, and everyone seems relieved that arithmetic has finally settled the case. One spouse is receiving $100,000 in cash. The other is getting a traditional 401(k) with a $100,000 balance.
Equal, right?
The IRS, an uninvited but remarkably persistent participant, may have a different opinion.
The problem is not that retirement accounts are bad assets or that every retirement dollar should be discounted. It is that two identical numbers on a spreadsheet may represent very different amounts of spendable money. And for the spouse who needs a moving deposit by Friday, that difference is not academic.
The Spreadsheet May Be Balanced. The Deal May Not Be.
Money in a checking account is generally available to spend. Money in a traditional, pre-tax 401(k) is different. Withdraw it, and the taxable amount generally becomes ordinary income. Withdraw it too early, and an additional 10% tax may apply unless an exception saves the day. The account balance is not necessarily the amount the recipient can spend.
This is not just a theoretical concern. Texas Family Code § 7.008 expressly permits a court dividing marital property to consider whether a particular asset will be taxed and when the tax will be due. That does not mean there is some mandatory IRS haircut for every retirement account. There isn’t.
The question worth asking in mediation is simpler: What will this asset actually mean to the person receiving it, and when?
First, Figure Out Which Kind of Account It Is
Before anyone starts discounting a retirement account, ask whether the balance is traditional, Roth, or a mixture of the two. A 401(k) statement may contain both pre-tax and designated Roth money, and the distinction matters.
A traditional account generally postpones income tax until the money is withdrawn. Roth accounts start with after-tax contributions. A qualified Roth distribution can be entirely tax-free. But not every Roth withdrawal qualifies, and a Roth 401(k) does not follow exactly the same withdrawal rules as a Roth IRA.
Here is a particularly easy mistake: Roth IRA withdrawal rules generally treat regular contributions as coming out first. A nonqualified distribution from a designated Roth 401(k), by contrast, generally contains a proportional share of contributions and earnings. The earnings may be taxable, and potentially subject to the additional early-distribution tax. The IRS explains that distinction.
The five-year rules can also differ when Roth 401(k) money is rolled to a Roth IRA. In other words, the word “Roth” is a good start, but it is not the complete tax analysis. That’s why you should always ask for the account statement rather than settle the issue by looking at the account’s nickname.
The QDRO Exception That Is Easy to Lose
Now for the wrinkle that deserves its own conversation. Under Internal Revenue Code § 72(t)(2)(C), a qualifying distribution paid directly from an employer retirement plan to a spouse or former spouse as alternate payee under a QDRO is exempt from the additional 10% early-distribution tax. Ordinary income tax may still apply to the taxable portion.
But the exception applies to the plan distribution, not to every dollar that once passed through a QDRO. Consider three common paths for an award from a traditional 401(k):
1. Take a direct distribution from the plan. If the plan permits the payout and the QDRO is qualified, the alternate payee can receive the funds directly. The taxable amount is subject to income tax, but the QDRO exception generally removes the additional 10% early-distribution tax.
2. Roll the award directly into an IRA and leave it invested. A proper rollover generally creates no current income tax or early-distribution tax. The money remains earmarked for retirement, with tax generally due when taxable funds are withdrawn later.
3. Roll it into an IRA, then take the cash out early. The QDRO exception does not follow the funds into the IRA. A subsequent taxable IRA withdrawal before age 59½ generally faces ordinary income tax and the additional 10% tax, unless some other exception applies. The IRS is not sentimental about where the money used to live.
One qualification is important: a QDRO does not magically make every account immediately payable. Distribution rights and timing depend on the plan and the qualified order. Counsel should verify the particular plan’s rules rather than promise a check next week. The Department of Labor’s QDRO guidance makes that distinction clear.
IRAs Have Their Own Rules
An IRA is not divided through the employer-plan QDRO process. Instead, IRC § 408(d)(6) permits a nontaxable transfer of an IRA interest to a spouse or former spouse under a divorce decree or qualifying written instrument incident to it. The usual goal is a properly documented custodian-to-custodian transfer, not one spouse withdrawing the money and writing the other a check.
The transfer itself does not ordinarily create income tax. But if the receiving spouse then cashes out a traditional IRA before age 59½, the QDRO penalty exception is unavailable. Another exception might apply, but “it came from a divorce” is not one of them. Different paperwork, different rules, and potentially a very different amount of spendable cash.
What Does $100,000 Really Buy?
Consider a 35-year-old receiving $100,000 from a traditional 401(k). For illustration only, assume the additional federal income tax caused by a $100,000 taxable withdrawal would be $24,000, and assume no other exception to the early-distribution tax applies. That $24,000 is an assumed tax calculation, not an instruction to multiply every account balance by someone’s marginal bracket.
Direct QDRO cash-out: $100,000 less $24,000 of federal income tax equals approximately $76,000 of after-tax spending power. The QDRO exception eliminates the additional 10% tax. For an eligible rollover distribution paid in cash, mandatory federal withholding is generally 20% of the taxable portion; withholding is a prepayment, not the final tax bill. IRS withholding guidance explains the distinction.
Direct rollover and hold: The full $100,000 can generally remain invested in the IRA with no current income tax. It would be wrong to call that $76,000 in today’s spendable cash, and just as wrong to pretend that taxes due decades from now have exactly the same effect as taxes due today.
Rollover, then early IRA withdrawal: Using the same assumed $24,000 income-tax cost, add $10,000 for the 10% early-distribution tax. The illustrative spending amount becomes approximately $66,000.
Same starting balance. Three different outcomes. This is a conversation the spreadsheet didn’t have.
Please don’t treat those figures as a ready-made valuation formula. Federal income tax is progressive, a large distribution may cross tax brackets, and the result depends on other income, basis, deductions, timing, and applicable exceptions. If the account will stay invested for another twenty years, a flat 24% deduction today is not a reliable present-value calculation. For a meaningful tax-affected valuation, counsel should involve a CPA, CDFA, or other qualified professional when warranted.
Liquidity Has a Value of Its Own
Even after dealing with taxes, one more issue remains: access. Cash in the bank can pay the movers on Friday. An award of retirement benefits may require counsel to obtain a signed QDRO, submit it for qualification, and wait for the plan’s distribution process. That can take time, and an otherwise perfectly good award might not solve an immediate cash problem.
So before everyone declares victory and closes their laptops, counsel should know what type of account is being awarded, whether the recipient plans to keep it or withdraw it, whether the plan actually permits the intended distribution, and whether the client needs cash sooner than the plan can deliver it. The tax professional can supply the numbers. Counsel needs to make sure the settlement reflects the bargain the parties actually intend.
The Bottom Line
A hundred thousand dollars in a checking account and a hundred thousand dollars in a retirement plan may look identical on a spreadsheet. They do not necessarily feel identical when somebody tries to pay the rent. Taxes matter. Timing matters. So does the simple question of whether the money can be accessed at all.
No one needs to turn a half-day mediation into a graduate seminar in retirement taxation. But five minutes spent before mediation asking the right questions can save the parties from making an expensive assumption dressed up as arithmetic.
If you’re working through retirement account division or another property issue with more moving parts than the spreadsheet suggests, we would be glad to help in mediation. You can schedule a half-day mediation session to get started, or book a full-day session if you already know the case needs it. Better to discover the difference at the mediation table than after somebody has spent the money.
This article provides general information, not legal or tax advice. The plan documents, current tax law, and the client’s circumstances should be verified before counsel relies on a particular calculation. Always do your own due diligence!